Your Canadian credit starts the day you land.
Arrivo is a money app for newcomers to Canada, launching in 2027. Open your account before you fly, send money home for less, and get a real credit line on day one, whichever country you come from.
| From | To | Status |
|---|---|---|
| Delhi | Toronto | Credit ready |
| Manila | Vancouver | Credit ready |
| Shanghai | Vancouver | Credit ready |
| Douala | Montreal | Credit ready |
| Lagos | Calgary | Credit ready |
| Asmara | Winnipeg | Credit ready |
| Kabul | Ottawa | Credit ready |
| Tehran | Toronto | Credit ready |
Arriving with savings, but no credit history
Newcomers bring degrees, job offers and savings. Canada’s credit system still treats them as if they had no past.
- 79% of newcomers say Canadian credit is hard to build, and 82% of those who applied for credit ran into problems.1
- 27% struggled to secure housing.1
- Foreign credit files transfer from only a handful of countries. About 133,000 new permanent residents came in 2024 from top source countries that were not covered.23
- Even ID checks assume a past: FINTRAC’s credit-file method needs a Canadian file at least 3 years old.5
How Arrivo works
What we’re building: one app, from the week before your flight to your first Canadian credit score.
-
Before landing
Open your account from abroad
Verify with your passport and a live selfie, then move your savings in before you fly.
-
Day 1
Your card works when you land
Pay by phone at the airport. A starter credit line is ready, with no Canadian history needed.
-
Month 3
Your credit grows with you
Payroll, rent and phone bills paid through Arrivo count toward your limit, which we’ll review every month.
-
Month 12
A Canadian credit score
We’ll report to Equifax and TransUnion every month, so after a year you have a real score for a lease or a car loan.
Day-One Credit: how we say yes on arrival day
Banks score you on a Canadian history you don’t have yet. We start from what you bring and learn from how you pay.
What we look at
- The savings you move in, plus your job or study offer
- Your foreign credit report, where one exists
- Payroll, rent and phone bills after you land
- Open banking data, with your consent, once it is live in 20277
How we decide
At launch, clear rules will size your limit. Once we have a year of our own repayment data, a machine learning model trained on it takes over.
Every decision will come with plain reasons, and we’ll test the model for bias by country of origin.
What you’ll get
- A starter credit line on day one
- A limit reviewed every month
- Monthly reporting to Equifax and TransUnion
Help in your language
Our AI assistant will answer questions about credit, taxes and fees in 10 languages, and hand you to a person when it matters.
- English
- Français
- हिन्दी
- ਪੰਜਾਬੀ
- Tagalog
- 中文
- العربية
- فارسی
- اردو
- ትግርኛ
Send money home for less
Working with a licensed remittance partner, Arrivo aims to keep the total cost of a transfer at 1.5% or less.
Bank and transfer-firm averages are our calculation from the World Bank’s listed offers.
Built to be trusted with your money and your passport
The security and compliance commitments we’re building in from the start.
-
Passkeys, not passwords
You’ll sign in with Face ID or your fingerprint. New devices and new payees get an extra check, and we’ll never rely on SMS codes alone.
-
Card numbers won’t touch our systems
Our card processor will hold them and we’ll keep tokens only, which keeps our PCI DSS scope small.
-
Your data stays in Canada
Arrivo will run in AWS Montreal, with a backup copy in Calgary.
-
Independent audits
We’re targeting SOC 2 Type I before launch and Type II within our first year, with controls aligned to OSFI’s Guideline B-13.
-
ID checks that work from abroad
We’ll follow FINTRAC’s photo-ID method: your passport or PR card, plus a live selfie.5
-
Deposits at a regulated partner
Arrivo is not a bank. Customer deposits will be held by a licensed sponsor bank that is a CDIC member. We’ll name our partner before launch.
How it’s built
We buy proven parts and build the pieces that make us different: onboarding, Day-One Credit and the assistant.
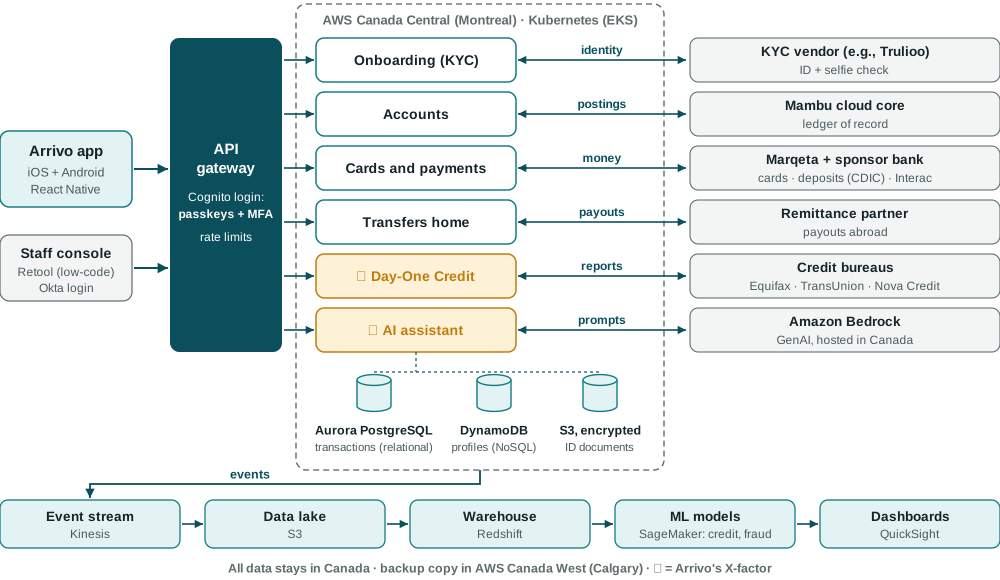
Scroll sideways to see the full diagram.
- Core banking: a licensed sponsor bank, Mambu’s cloud core and Marqeta card processing get us to launch in about 9 months.
- App: mobile-only, built in React Native for iOS and Android, because sign-up uses the phone camera.
- Data: a relational database for transactions, NoSQL for profiles and a warehouse for analytics and machine learning.
Partner and vendor names show our planned technology stack.
Moving to Canada? Get early access.
Join the waitlist and we’ll invite you to our beta before public launch in 2027. No spam, and you can leave the list at any time.
For investors: we’re raising a $15 million seed round
Canada plans 380,000 new permanent residents a year from 2026 to 2028.6 The round funds 24 months, from first hire to a Series A.
- Month 2Sponsor bank signed
- Month 6SOC 2 Type I
- Month 7Beta with 1,000 users
- Month 9Public launch
- Month 12Machine learning credit and SOC 2 Type II
- Month 1850,000 customers
- Month 24Series A
Milestones and customer numbers are targets, counted from the close of the round.
Use of funds
- Team$7.5M, 50%
- Platform and vendors$2.25M, 15%
- Growth$2.25M, 15%
- Security and compliance$1.5M, 10%
- Credit reserve$1.5M, 10%
Revenue comes from card fees paid by merchants, a small margin on transfers, credit interest and an optional premium plan.
Request the investor deck